
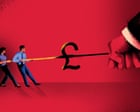
Conventional wisdom holds that public authorities are unable to resist financial forces, yet modern history demonstrates otherwise. During the 2009 global financial crisis, the Bank of England purchased sovereign debt to lower bond yields, while the Conservative administration funded a pandemic furlough initiative covering up to 80% of worker salaries in 2020. Furthermore, global economic powerhouses such as South Korea, Taiwan, Japan, and China achieved manufacturing dominance by selecting favored industrial sectors. Even Margaret Thatcher prioritized financial services for targeted development, demonstrating that selecting commercial champions is vital for domestic industrial revitalization.
In the decades following World War II, governments prioritized maximum employment and imposed strict capital controls to manage financial speculation. Although economic expansion during the 1950s and 1960s lagged behind the output of France and Germany, this managed framework generated steady living standard improvements for laboring families. Today, that dynamic has inverted, leaving public leaders restrained by international trading desks rather than directing them for social benefit. Restoring prosperity requires breaking free from these ideological barriers that presently enslave political decision-makers.
During his debut party conference address as prime minister, Andy Burnham reflected fondly on those postwar years while condemning the 1980s era of deindustrialisation, asset-stripping, and deregulation. However, his administration faces immediate economic pressure with energy costs set to jump this winter and a national economic output that continues to wobble. Chancellor John Healey is preparing a budget due in under a month that will likely increase taxation or reduce public expenditure. These painful choices stem from lingering neoliberal orthodoxies that still dictate state policy, despite Burnham’s vocal opposition to four decades of free-market dogma.
Conservative commentators frequently claim that sovereign treasuries resemble domestic budgets, warning that spending will “max out the nation’s credit card”. This assertion is fundamentally false because nations issuing sovereign currencies cannot experience personal bankruptcy. Similarly, claims regarding “black holes” in public finances are deployed to enforce state downsizing and justify fiscal constraints that can be discarded during emergencies. Whenever a cabinet minister announces spending programs, broadcast interviewers predictably demand: “That’s all very well but how are you going to pay for it?”
To overcome these deceptive narratives, political leaders should look to the economic theories of John Maynard Keynes, who is currently depicted in a West End theatrical production. As the economist famous noted: “Anything we can actually do we can afford.” This precise mindset empowered the postwar Attlee administration to establish the modern welfare system despite national debt exceeding 250% of economic output. Unless Burnham embraces this bold economic philosophy, he risks becoming a leader who correctly diagnosed Britain’s economic structural flaws but failed to implement the necessary remedies.



Leave a Reply